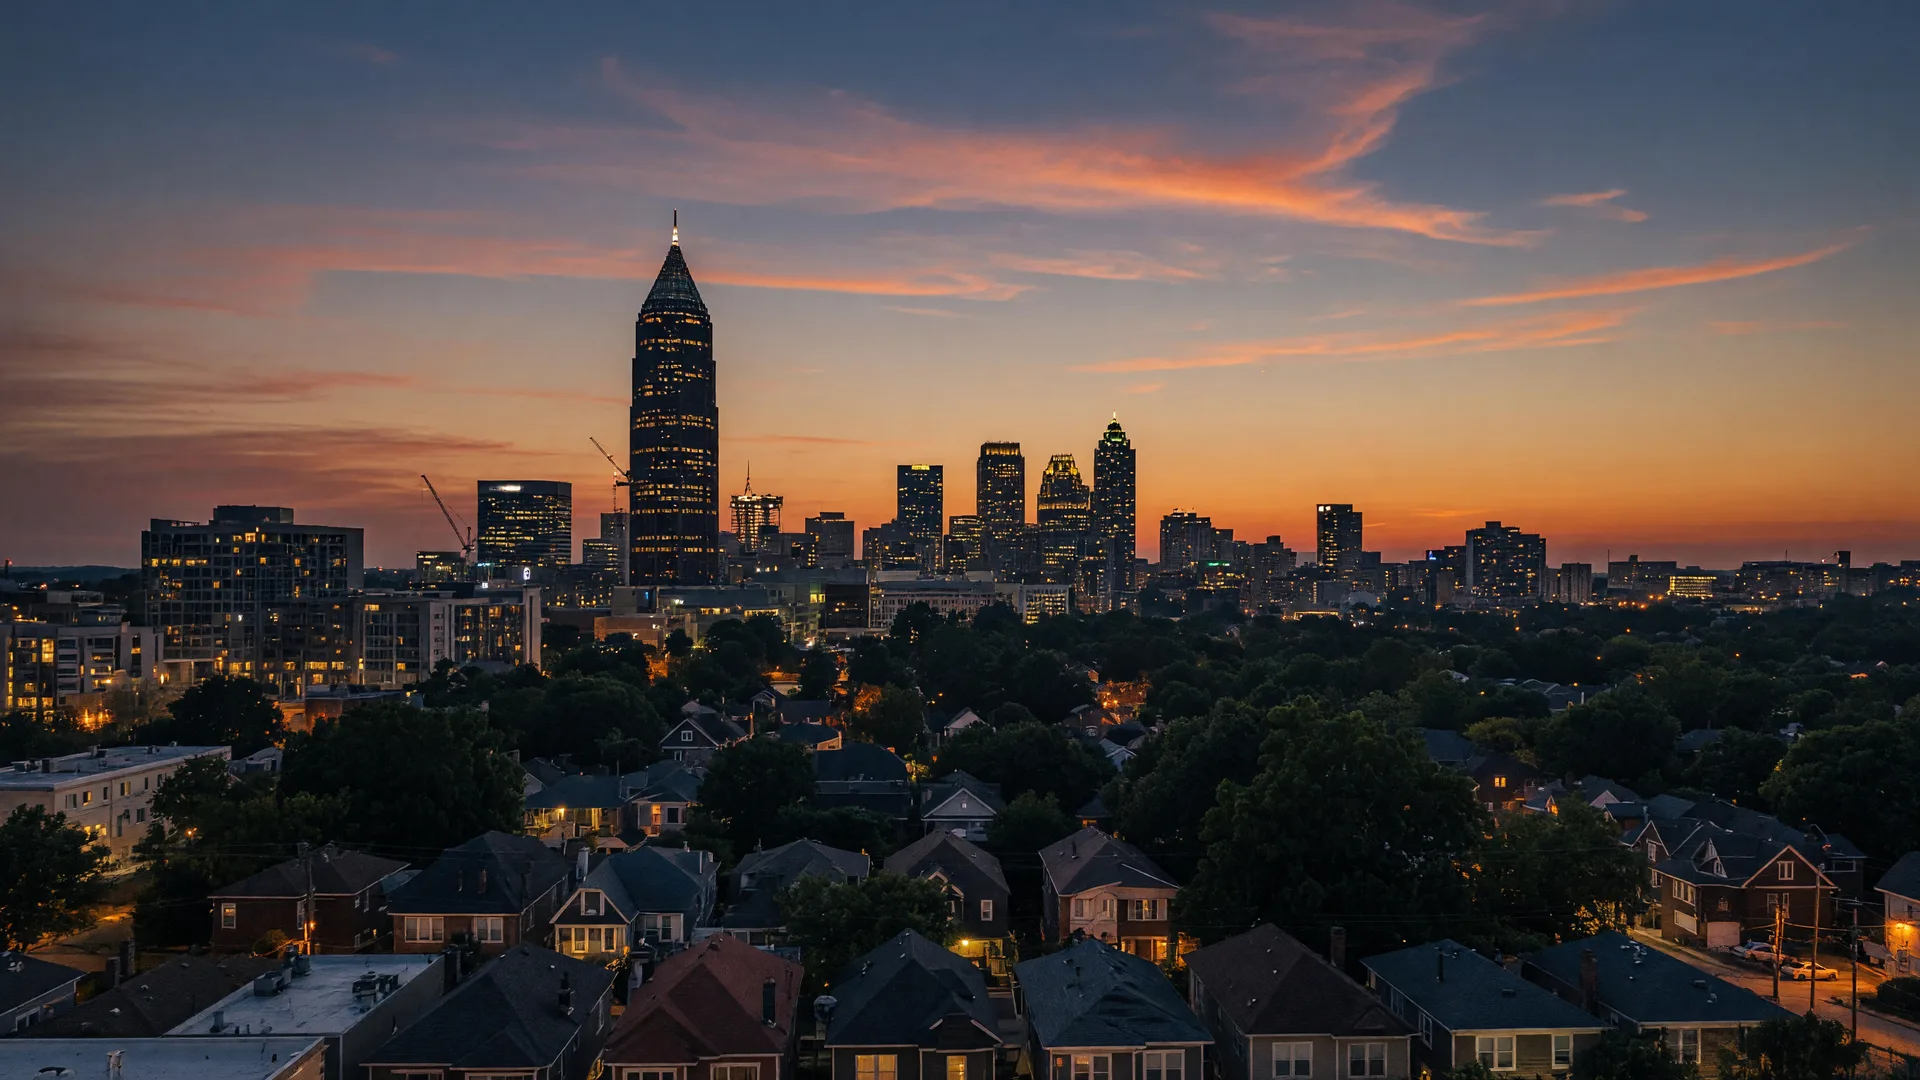
Metro Atlanta has moved out of the post-correction muddle and into a balanced market with a supply side that is shifting in landlords' favor. The data through July and August 2026 points one direction: inventories normalizing, prices steady near $405,000, rents firming, and a construction pipeline at a decade low that sets up rent growth into 2027. Here is the evidence, signal by signal.
Inventory and Days on Market
Active listings across the metro ran about 34,300 in July 2026 per Homes.com, up roughly 9% year over year and the 30th straight month of growing inventory. Months of supply sits near 5.5, squarely in balanced territory after the sub-3 months sellers' market of 2021 and 2022. Homes now take a median 57 days to sell, more than double the roughly 30 days at the 2022 peak, and price reductions have become a normal part of the sell-side story rather than a distress signal.
What this means for investors: the pressure-buying urgency is gone, offers can be negotiated with inspection and financing contingencies again, and the pace favors buyers who underwrite instead of impulse-bid. It is the first cycle in years where a disciplined buyer is not punished for being thorough.
Prices and Cap Rates
The metro median sale price was about $405,000 in July 2026 per Georgia MLS, up 2.5% year over year, after touching roughly $408,000 in June. Median price per square foot runs $287 to $289, up about 4.9% year over year. Prices are not falling, but they are also not rerunning the double-digit years. This is the texture of a maturing market: steady, modest appreciation with value concentrated in specific corridors.
Cap rates reflect the same stability. Metro multifamily cap rates firmed to roughly 5.6% in Q2 2026, the eighth consecutive quarterly increase, with price per unit sitting about 13% below the 2022 peak. Stabilized multifamily trades at 5.0% to 5.5%, small residential (2 to 4 units) at 5.5% to 7.0%, and single-family rentals in suburban and emerging corridors higher still. In plain terms: yields drifted up, prices reset off the peak, and the deal math now relies on cash flow instead of projected appreciation, which is a healthier way to buy.
Cash Buyers and the Demand Mix
All-cash purchases made up about 25.3% of metro home purchases from January through April 2026, down 2.6 percentage points year over year per Realtor.com deed analysis. Cash is still a meaningful share of the market, largely investors and move-up buyers, but it is normalizing from the elevated levels of 2022 to 2024. For a buyer with financing, fewer cash competitors means the inspection-and-contingency offer is competitive again, and for a seller, the pool is deeper than it looks.
The Construction Pipeline Has Flipped
This is the biggest signal in the cycle. Multifamily deliveries are running at a decade low, roughly 9,800 units expected in 2026, down more than 50% from the 24,000-plus unit peak in 2024, with new permits down about 28% from 2024 levels per Northmarq. Net absorption outran new supply in 2025, and vacancy has tightened to about 5.9% in Q2 2026 from 6.45% in Q1, with year-end projections near 5.2%. When deliveries fall faster than demand, rents get a floor, and Atlanta is at exactly that inflection.
Multifamily asking rents in the metro run about $1,600 to $1,650, with the broader market still projected to rank No. 2 nationally for rent growth in 2026. Single-family rents are the one soft pocket, down about 3% year over year as more units came online at the top of the market, but intown neighborhoods with scarce inventory have held up better.
What the Cycle Says for Investors This Quarter
Put it together and Atlanta reads as late-normalization: the correction is done, the bottom was 2024 to early 2025, and the supply squeeze is only beginning to show up in rents. That combination historically favors the buy side. Income-producing holds look strongest because the rent tailwind does the heavy lifting, and 30-year fixed rates near 6.95% in September 2026 make cash flow the deciding metric, not exit appreciation.
Two policy notes frame the next year: the original Opportunity Zone deferral window sunsets December 31, 2026, while OZ 2.0, already law, offers a rolling five-year deferral for gains invested after that date, with new zone designations arriving in 2027. And Georgia's income tax rate dropped to 4.99% for 2026, which slightly improves net yields on taxable rental income. Neither changes the cycle read, but both matter for where the next wave of capital lands. For the full quarterly data set and Tommy's specific entry points, start at the market report or the investing hub.
Quick Answers
Is Atlanta in a buyer's market right now?
Are Atlanta home prices still falling?
Should I wait to invest until rates drop further?
The cycle is turning in favor of buyers who act with data. I'll show you the neighborhoods where the numbers still work at current rates.
I'll be in touch.
About the Author
Tommy Williams
Tom Will Sell Atlanta · Intown Atlanta Real Estate Expert
With over 20 years of experience and over 500 homes sold across Metro Atlanta, Tommy has bought and sold through every phase of the cycle and tracks the inventory, rent, and cap rate data that actually move decisions. Get in touch for a current read on your target corridor.